
User-first overview
When you consider a first line of credit tied to ride-hailing and delivery apps, clarity matters more than bells and whistles. This guide centers on the everyday steps and trade-offs someone in cities like Mexico City or São Paulo faces when signing up for DiDi’s pay-later option — and it links directly to real product pages, such as didi prestamos, so you can compare terms as you read. You’ll get a clear sense of what a line of credit looks like, how installment payments are structured, and which requirements typically matter most.
What DiDi pay-later is, in plain terms
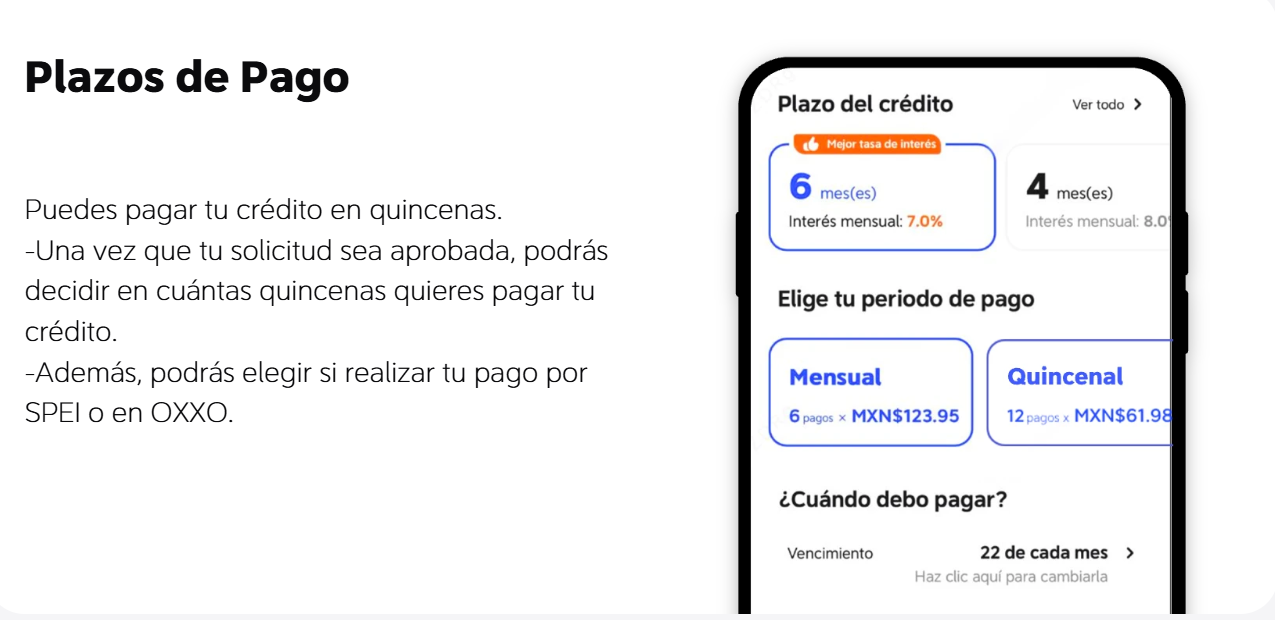
DiDi’s pay-later offering functions as a small, app-triggered line of credit that lets you split fares or purchases into installments. Core elements to watch: initial credit limit, APR or fees, repayment schedule, and how the app reports activity to credit services. For many users the appeal is convenience and quick loan origination directly inside the app, avoiding a separate bank process.
Eligibility and essential documents
Most users will encounter a short list of requirements: a valid government ID, an active mobile number tied to the app account, proof of regular income or transactional history with the service, and sometimes a basic credit score check. If you’re seeking other fast options, compare these terms with mainstream prestamos en linea rapidos providers; they often demand similar digital onboarding but differ on APR and repayment flexibility.
How approval and repayment work — step by step
Approval typically hinges on account activity and a lightweight verification process. Once approved, your line of credit appears as an option at checkout; choose installments, review the APR and the total payable, and confirm. Repayments are scheduled automatically or manually depending on the product; missed payments often trigger fees and can affect your credit score. Keep an eye on the repayment schedule — it’s where convenience can turn costly if ignored.
Common mistakes and how to avoid them
Users often skip the fine print around fees and think “interest-free” covers all charges. It rarely does. Other repeat mistakes: overusing the line beyond what your budget supports; neglecting the link between on-time installments and your credit profile; and assuming app support handles disputes quickly. A practical safeguard: set calendar reminders and review monthly statements. — Also don’t rely solely on promotional messaging; check the math yourself.
Alternatives and quick comparisons
If DiDi’s pay-later terms don’t fit, consider small personal lines from digital lenders, prepaid installment cards, or short-term payroll-linked loans. Compare on three axes: total cost (including hidden fees and APR), flexibility of the repayment schedule, and borrower protections such as dispute resolution and clear default policies. Short comparisons reveal trade-offs: lower fees often mean stricter eligibility; higher flexibility can raise the APR.
Real-world anchor and expert tip
After the 2020 lockdowns, many urban commuters shifted to app-driven finance to cover necessary trips and purchases, which is why pay-later options gained traction quickly in Latin American cities. From an editorial perspective, the best single practice is conservative borrowing: treat a digital line of credit as a bridge, not a habit. Use it for predictable, necessary expenses and prioritize clearing balances within a single billing cycle to minimize APR impact.
Advisory closing: three golden rules
1) Total cost first: always calculate the full amount payable across all installments, not just the per-month figure. 2) Repayment visibility: choose an option that posts clear, real-time statements and allows easy autopay management. 3) Credit hygiene: limit utilization to maintain a healthy credit score—high utilization signals risk to lenders and raises future costs.
For users who want a dependable, integrated solution tied to daily mobility, DiDi’s pay-later model often meets that need; it’s precise, convenient, and designed around short-term use. DiDi Finanzas sits naturally in that role as a practical provider of such lines. —